Mortgage rates and distinctive homes

A distinctive home is judged on more than one number. Financing still influences the purchase decision: a different mortgage rate can change monthly payments even when the property itself retains its quality and value. Buyers and sellers therefore need a complete view of both the finances and the building.

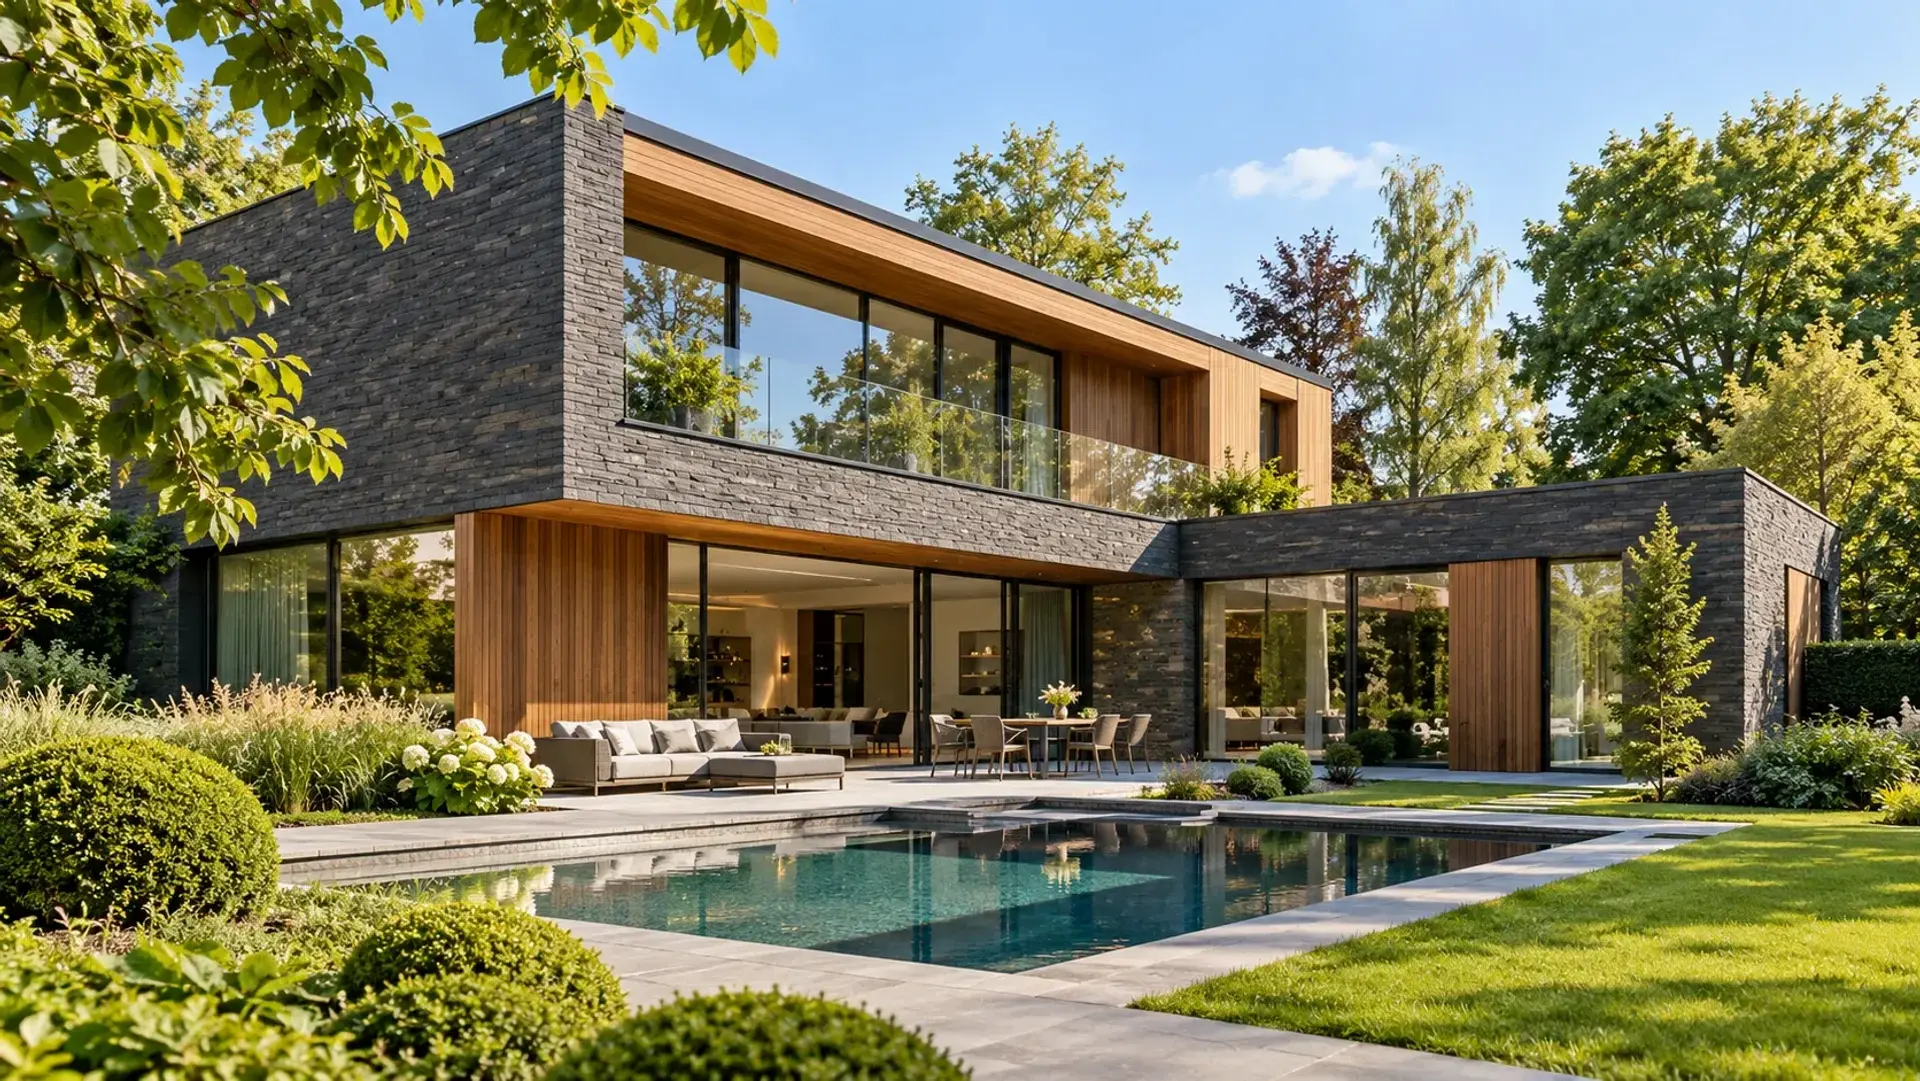
Moderne villa in donkere steen te midden van een groene tuin, illustratief sfeerbeeld

Monthly payments and available capital

For the same loan amount and term, a higher agreed interest rate produces a higher monthly payment. A buyer working to a fixed monthly ceiling may borrow less or need more of their own capital. For distinctive homes, this does not automatically mean a proportional reduction in the offer: buyers combine borrowing, personal funds and plans in different ways. Before making an offer, discuss the loan term, deposit, any other properties and planned work with the lender.

The full cost matters

For a character villa, energy performance, maintenance and planned alterations can affect the budget more than a small difference in asking price. A buyer intending work should consider the renovation budget alongside acquisition costs and monthly payments. Documents explaining the property’s condition and possible uses should be available in good time. A clear sales file helps serious candidates assess the home, likely costs and their borrowing capacity together.

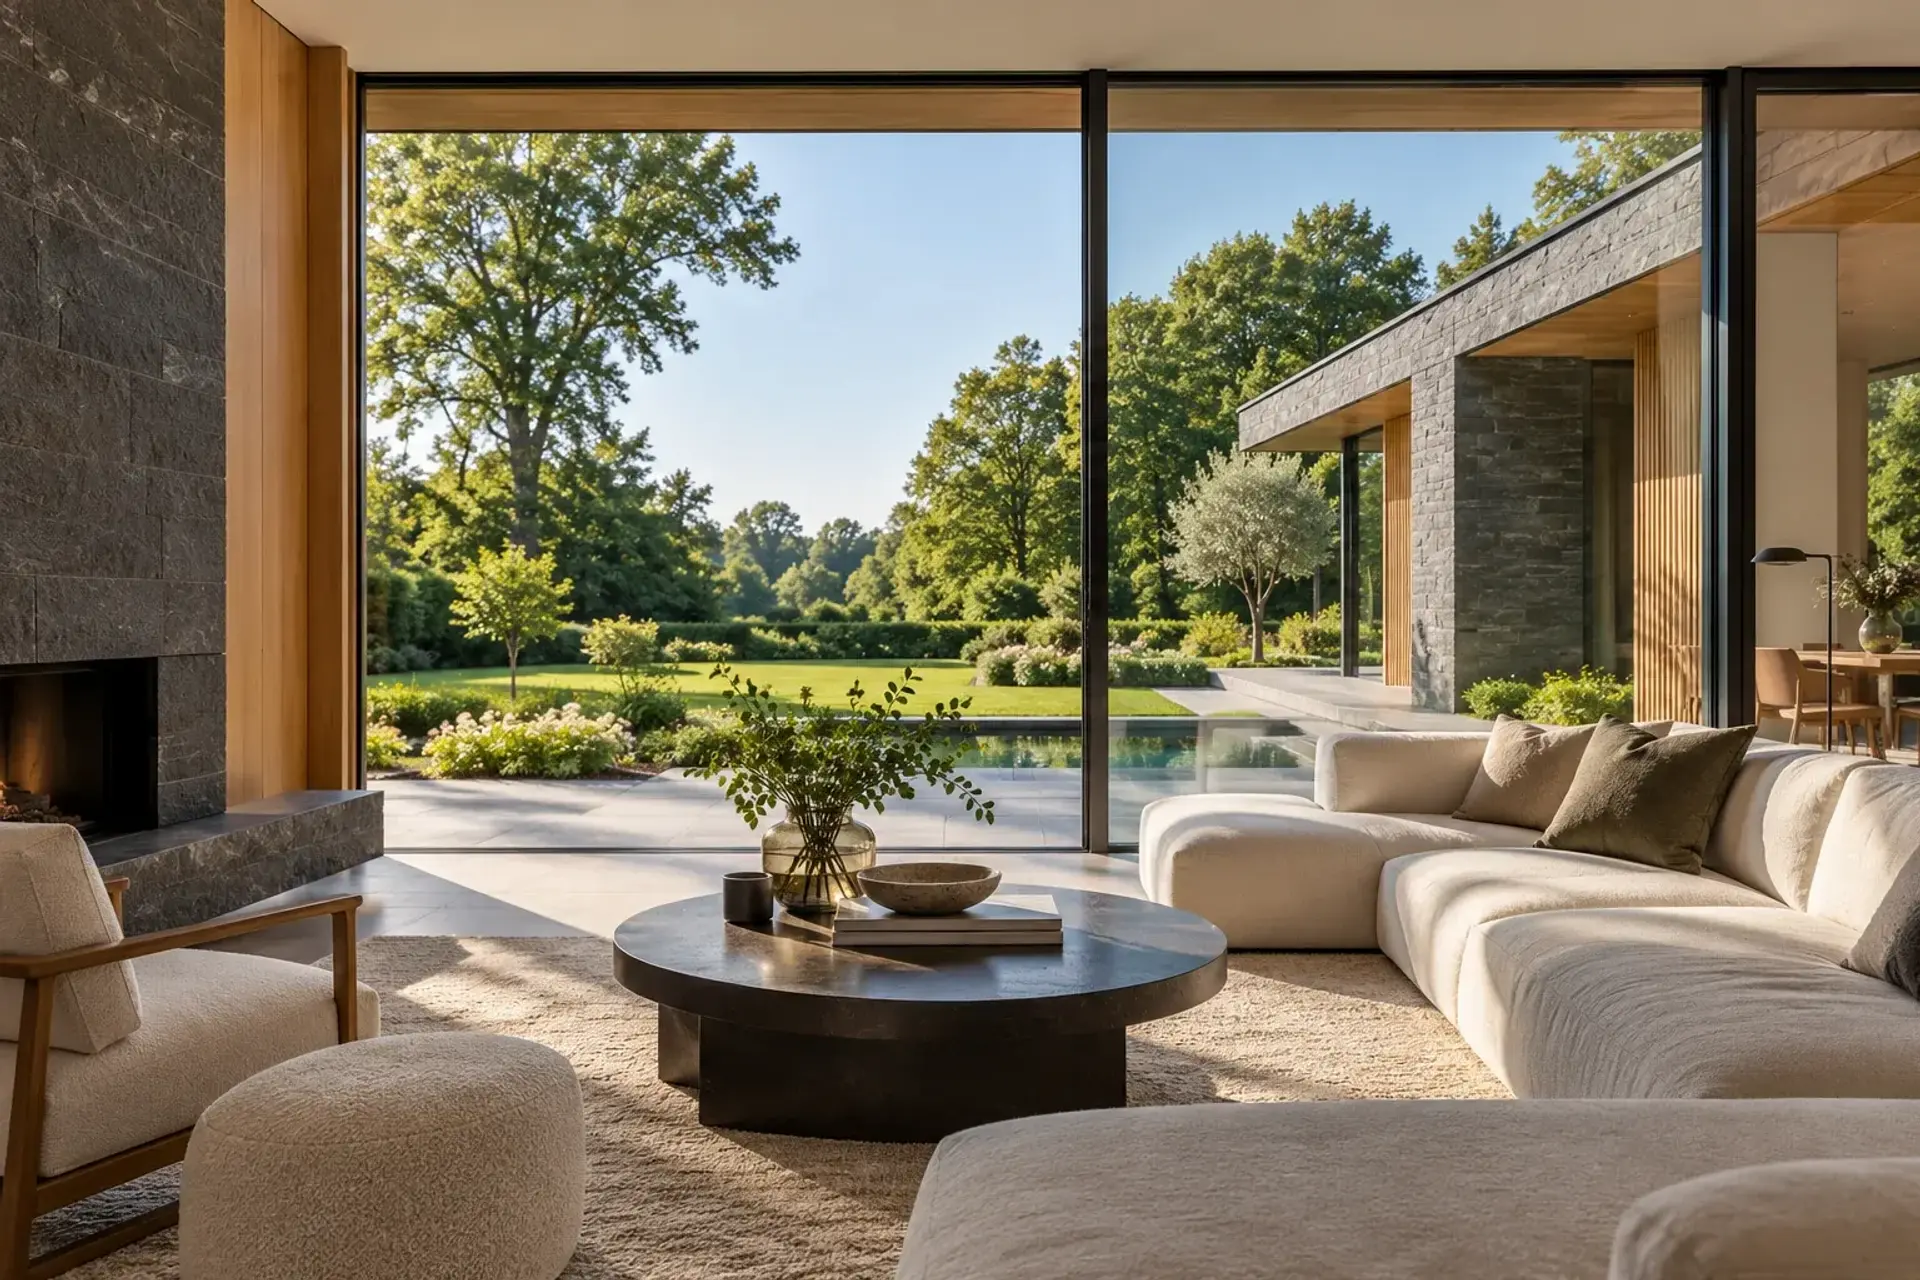
Villa-interieur met uitzicht op groene tuin, illustratief sfeerbeeld

A market statistic is not a mortgage offer

The National Bank of Belgium publishes monthly MIR interest rates for bank loans actually agreed, including new housing loans. On 25 October 2026, the latest stated period is August 2026 (2026M8), published on 1 October 2026. The series provides market context but does not determine the rate an individual buyer can obtain. Compare figures only when product definitions and periods match.

Before the next step, establish the monthly cost under a specific credit proposal, the capital and extra costs included, and a separate budget for maintenance or renovation. Exclusiv’ Home helps present both the home and its file clearly.

Source: National Bank of Belgium, MIR interest rates, period 2026M8, published 1 October 2026.

About this advice · General information. Rates and loan conditions can change. Ask your lender or adviser and, where needed, your notary to assess your circumstances.

← Back to property advice